TR
 EN
What Is Comprehensive Car Insurance? What Are the Advantages of Having It?
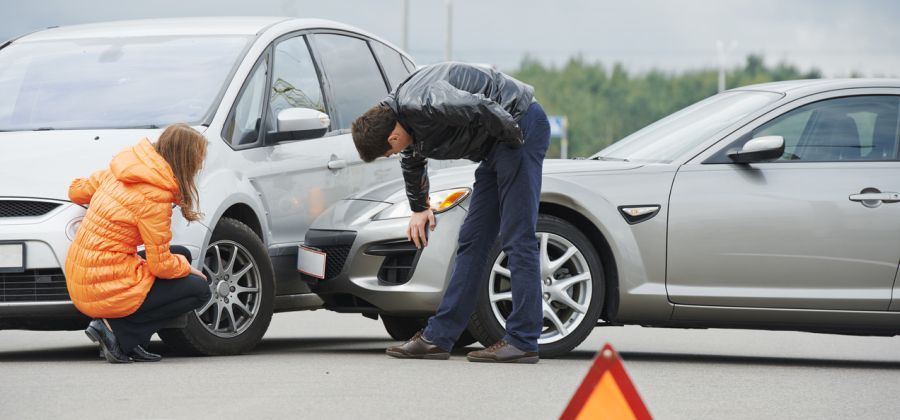
Owning a car comes with many potential expenses, and unexpected damage can sometimes create a significant financial burden. A traffic accident, theft, fire, natural disaster, vandalism, or even severe weather can cause expensive damage to a vehicle.
This is where comprehensive car insurance, commonly known as Kasko in Turkey, becomes important. Unlike mandatory third-party liability insurance, which primarily protects against damage caused to other people or their property, comprehensive insurance is designed to protect the insured vehicle itself.
The exact coverage depends on the policy, but comprehensive insurance can provide financial protection against many different risks.
What Is Comprehensive Car Insurance?
Comprehensive car insurance is an optional vehicle insurance policy that protects the owner's vehicle against specified risks.
Depending on the policy, it may cover damage resulting from:
-
Traffic accidents
-
Theft
-
Attempted theft
-
Fire
-
Natural disasters
-
Flooding
-
Hail
-
Storms
-
Vandalism
-
Falling objects
-
Animal-related accidents
-
Glass damage
-
Other risks specifically included in the policy
The important point is that comprehensive insurance does not mean that every possible type of damage is automatically covered.
The coverage, exclusions, deductibles, limits, and additional services depend on the insurance contract.
What Is the Difference Between Kasko and Traffic Insurance?
This is one of the most important points for vehicle owners to understand.
Third-party liability insurance is generally designed to cover damage that you cause to other people or their property as a result of an insured accident.
Comprehensive insurance, on the other hand, is primarily concerned with protecting your own vehicle against the risks specified in your policy.
For example, imagine that you cause an accident and your own vehicle is seriously damaged.
Third-party liability insurance may cover the damage you caused to the other party, subject to its terms and limits, but it does not automatically mean that the damage to your own vehicle will be repaired.
If your comprehensive policy covers that type of accident, it can provide protection for your own vehicle.
This difference is why having only mandatory liability insurance may leave the owner financially exposed when their own vehicle is damaged.
What Does Comprehensive Insurance Usually Cover?
The exact coverage varies between insurance companies and policies, but comprehensive vehicle insurance can include several important protections.
Accident damage
Depending on the policy, damage caused by a collision may be covered even when the insured driver is responsible for the accident.
Theft
If the vehicle is stolen, the policy may provide compensation according to the conditions and valuation rules specified in the contract.
Attempted theft can also cause damage to locks, doors, ignition systems, windows, or other components, and these damages may be covered when included in the policy.
Fire
Vehicle fires can cause extremely expensive damage. Depending on the policy, fire-related losses may be covered.
Natural disasters and severe weather
Hail, flooding, storms, earthquakes, falling trees, and similar events may cause significant vehicle damage. These risks can be included in comprehensive insurance coverage.
Vandalism
Intentional damage caused by another person may also be covered under certain policies.
Glass damage
Windshield and other glass damage may be covered, although the conditions and deductible can vary considerably between policies.
What Is Usually Not Covered by Kasko?
Comprehensive insurance does not mean unlimited protection.
Common exclusions can include normal wear and tear, routine maintenance, mechanical deterioration, and certain types of misuse.
For example, worn brake pads, an old battery, a worn clutch, or an engine component that fails simply because of normal use would not normally be treated as an insured accident.
Similarly, a policy may exclude certain situations or impose specific conditions for particular types of damage.
This is why it is important to read the policy rather than assuming that every vehicle problem will be paid for by the insurance company.
What Are the Advantages of Having Comprehensive Insurance?
The biggest advantage is financial protection against unexpected vehicle-related losses.
A relatively small annual insurance premium can protect the owner from potentially very large repair or replacement costs, depending on the vehicle and policy.
Some of the most important advantages include the following.
Protection Against Expensive Accident Damage
Modern vehicles contain expensive electronic systems, sensors, cameras, headlights, airbags, body panels, and safety components.
Even a relatively ordinary accident can therefore result in a surprisingly high repair bill.
Comprehensive insurance can reduce the financial impact when the damage falls within the policy's coverage.
This can be particularly valuable for newer vehicles or vehicles with expensive replacement parts.
Protection Against Vehicle Theft
Vehicle theft can result in a much larger financial loss than an ordinary repair.
If a stolen vehicle cannot be recovered, the financial consequences can be substantial.
A suitable comprehensive policy can provide compensation according to its terms, helping the vehicle owner avoid carrying the entire loss alone.
Protection Against Hail and Severe Weather
A vehicle parked outside can be exposed to risks that have nothing to do with the driver's actions.
Hail can leave dozens or even hundreds of dents on a vehicle. Floodwater can damage electrical systems, interior components, and mechanical parts.
Strong storms can also cause damage through falling branches or other objects.
Coverage for these events can be particularly useful in areas where severe weather is common.
Protection Against Fire
A vehicle fire can result in extensive damage within a very short period.
The cause may involve an electrical fault, fuel-system problem, an external fire, or another covered event.
If fire protection is included in the policy, comprehensive insurance can provide important financial support following such a loss.
Protection Against Vandalism
A vehicle can be damaged even while it is parked safely.
Scratches, broken windows, damaged mirrors, intentional body damage, or other acts of vandalism can result in expensive repairs.
Depending on the policy, these types of losses may be covered.
Financial Planning Becomes Easier
One of the less obvious benefits of comprehensive insurance is that it can make unexpected vehicle expenses easier to manage.
Without insurance, a major accident could require the owner to pay a large repair bill at once.
With appropriate coverage, the owner generally has a known premium and may have a deductible or other out-of-pocket amount when making a covered claim.
This makes major unexpected losses easier to plan for.
Is Kasko Worth Having on an Older Car?
There is no universal answer.
The decision depends on the vehicle's current value, insurance premium, deductible, the owner's financial situation, and the risks associated with where and how the vehicle is used.
For an expensive or relatively new vehicle, comprehensive insurance can be easier to justify because the potential financial loss is substantial.
For an older vehicle with a relatively low market value, the annual premium may represent a larger percentage of the vehicle's value.
In that situation, the owner may decide that paying for insurance is less attractive than accepting the financial risk personally.
What Is a Deductible?
Some comprehensive insurance policies include a deductible or excess.
This is the amount that the insured person is responsible for paying when an applicable claim is made, while the insurer covers the remaining eligible amount according to the policy.
For example, if a covered repair costs a certain amount and the policy has a specified deductible, the owner may have to pay that portion while the insurer covers the rest.
A higher deductible can sometimes reduce the insurance premium, but it also means a higher out-of-pocket cost when a claim is made.
Does Having Kasko Mean Every Accident Will Be Paid?
No.
This is a common misunderstanding.
Insurance companies evaluate claims according to the policy terms, coverage limits, exclusions, deductibles, and circumstances of the incident.
There may also be special conditions relating to the driver's license, vehicle use, modifications, declared information, or other circumstances.
Therefore, the cheapest policy is not necessarily the best policy.
A policy with a lower premium may also have narrower coverage or higher out-of-pocket costs.
What Should You Check Before Buying Kasko?
The price should not be the only factor when comparing policies.
It is important to check:
-
Which types of accidents are covered
-
Theft and attempted theft coverage
-
Fire coverage
-
Natural disaster coverage
-
Flood and hail coverage
-
Glass coverage
-
Vandalism coverage
-
Deductible amounts
-
Repair and replacement conditions
-
Authorized or non-authorized repair facilities
-
Original or alternative replacement parts
-
Towing and roadside assistance
-
Replacement vehicle availability
-
Coverage limits
-
Exclusions
-
Vehicle valuation rules
-
Special conditions for accessories and modifications
These details can make a major difference when a claim actually occurs.
Why Is the Repair Network Important?
The insurance company's repair network can affect the repair experience considerably.
Some policies may allow repairs at authorized dealerships, while others may direct the vehicle to contracted repair centers.
For newer vehicles, the quality of the repair can be particularly important.
A vehicle equipped with radar sensors, cameras, parking sensors, LED headlights, or advanced driver-assistance systems may require specialized equipment and calibration after an accident.
A cheap repair is not necessarily a good repair if safety systems are not restored correctly.
Does Kasko Cover Mechanical Failures?
Generally, comprehensive vehicle insurance is not intended to function as an extended mechanical warranty.
If an engine, transmission, turbocharger, air-conditioning compressor, or another component fails because of mechanical wear or an internal defect, comprehensive insurance will not automatically cover the repair.
The cause of the damage matters.
If a component is damaged as a direct result of a covered accident or another covered event, the situation can be different.
This distinction is important when deciding whether an unexpected repair is an insurance claim or a normal maintenance expense.
Is Comprehensive Insurance Necessary for Every Driver?
Not necessarily.
It is particularly useful for people who would have difficulty financially replacing or repairing their vehicle after a major loss.
It can also be attractive for owners of newer, expensive, or frequently used vehicles.
On the other hand, someone with an older, low-value vehicle and enough savings to comfortably absorb a major loss may decide that comprehensive insurance is not worth the annual cost.
The right decision depends on the balance between insurance cost and financial risk.
Kasko Provides More Than Just Accident Protection
The main purpose of comprehensive insurance is not simply to pay for accident repairs.
Its real value is the protection it provides against events that can cause a large and unexpected financial loss.
A stolen car, severe hailstorm, fire, flood, vandalism, or major accident can turn into a very expensive problem within minutes. Having appropriate insurance can significantly reduce the financial consequences of such events.
For this reason, when comparing Kasko policies, the important question is not simply “Which one is cheapest?” but rather “What protection will this policy actually provide when I need it?”